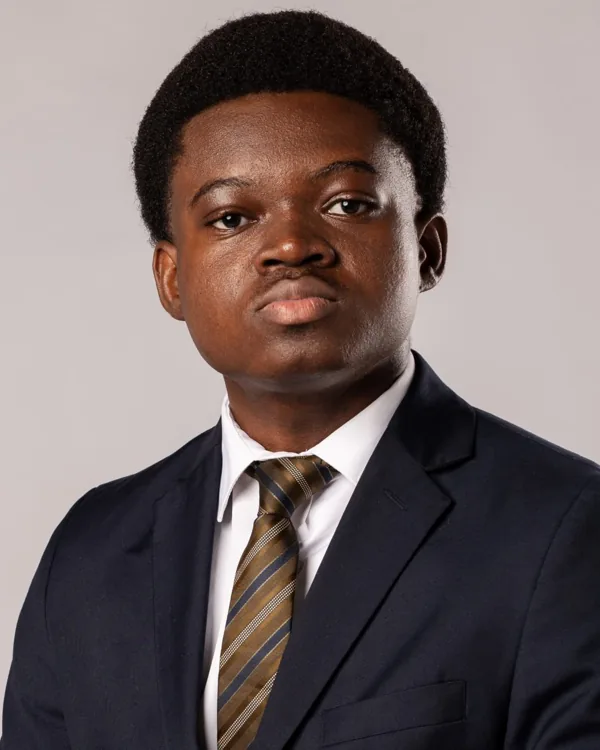
MSc Finance candidate at ENCG Casablanca, FMVA® and BIDA® certified, and a Yale Financial Markets certificate holder. On the CFA® Program, I am not yet registered and not a candidate. This is a project, not a current candidacy: I plan to register in summer 2027 and sit Level I in May 2028. Based in Casablanca, Burkinabè, and working in English and French.
My work is systematic portfolio management first, corporate finance second. Every project starts from a public filing or a named dataset, states its assumptions, and publishes its limits next to the result. The stack is Python, R, SQL, Linux, statistics and probability, with Power BI for reporting.
What I do in portfolio management
I build and test the chain a portfolio manager is accountable for — allocation, risk budgeting, security selection, hedging and attribution — on Casablanca and global market data. The work is long-only and multi-asset in its framing, and it treats liquidity and capacity as first-order constraints rather than footnotes.
- Allocation and risk. Policy portfolios, risk budgets, VaR and CVaR, drawdown, stress tests and the liquidity limits that decide whether a position can actually be exited.
- Fixed income. Bank Al-Maghrib curve fitting, bond pricing, duration and convexity, and key-rate hedging of a MAD sovereign book.
- Factor research. Pre-specified factors, transaction costs, rank IC, drawdowns and ADV-based capacity on BVC equities.
- Attribution. Brinson-Fachler, Carino linking and factor attribution, including the cases where the excess return does not survive the explanation.
- Derivatives. Option pricing, the SPX volatility surface, and the difference between delta and delta-gamma hedging.
Explore the portfolio-management projects →
What I do in corporate finance
I value companies from their filings and rebuild the mechanics behind the answer: the three statements, the debt schedule, the working-capital cycle and the assumptions that move the valuation. The output is a model that can be recomputed, not a slide that has to be trusted.
- Valuation. Linked three-statement models, DCF, WACC on market-value weights, terminal value and sensitivity analysis.
- Leverage. Sponsor LBOs with sources and uses, cash sweeps, interest limitations, management incentives and returns attribution.
- M&A diligence. Quality of earnings, EBITDA bridges, working capital, customer concentration and AR/AP aging.
- Accounting and FP&A. Trial-balance checks, accounting-quality flags, Power Query cleaning, star schemas and DAX measures.
Explore the corporate-finance projects →
Investment process
A portfolio manager is not paid to have views. A portfolio manager is paid to turn a mandate into a repeatable process, then defend every step of it. These are the five decisions the work is organised around.
Objective, constraints, horizon, liquidity needs and tolerance for loss — written down before a view is formed. The investment policy statement is the contract every later decision is judged against.
The policy portfolio sets the beta. Equity, fixed income, cash and alternatives are sized by horizon, liquidity and drawdown tolerance. It is the largest driver of long-run outcomes.
Bottom-up valuation inside the policy bands: DCF, comparables, screens and factor exposures. A thesis has to survive the filings before it earns a position, and a margin of safety before it earns size.
Covariance, position limits, concentration rules, factor exposures, VaR and CVaR, and stress tests. Risk is sized before the return case: the first question is what breaks the book.
Performance against the policy benchmark, Brinson and factor attribution, rebalancing discipline and written reporting. The record is the product: returns are explained, not merely reported.
The method behind the process is simple: source from the filing, label the rest; build the plumbing, not the slide; publish the audit, miss included; and ship the artifact or do not ship. No client capital is managed, and no performance is claimed.
CFA® Program — a project, not a candidacy
To be unambiguous: I am not yet registered for the CFA® Program and I am not a CFA candidate. This is a study project, not a current candidacy. I plan to register in summer 2027 and to sit Level I in May 2028.
I read the curriculum as desk work rather than a checklist: ethics and professional standards, quantitative methods, economics, financial statement analysis, corporate issuers, equity investments, fixed income, derivatives, alternative investments, and portfolio management and wealth planning.
The point is not the credential on its own. It is that the same ten domains show up in the projects: an IPS in the allocation work, fixed income in the BAM curve, financial statement analysis in the Akdital model, and ethics in the way every result is framed.
Roles I am looking for
I am looking for a full-time analyst seat on a portfolio management, research or risk team in Casablanca or remote:
- Asset Management Analyst
- Portfolio Analyst
- Investment Analyst
- Equity Research Analyst
- Risk Analyst
I also take select project-based financial modeling and valuation work. If you are hiring, or have a model that needs a second pair of hands, the work above is the application.
Contact
Email. yirviell.some@gmail.com
LinkedIn. in/yirviel-some
GitHub. github.com/yirvisom
CV. View the one-page CV · PDF