Portfolio ManagementLab EN
The Attribution Lab
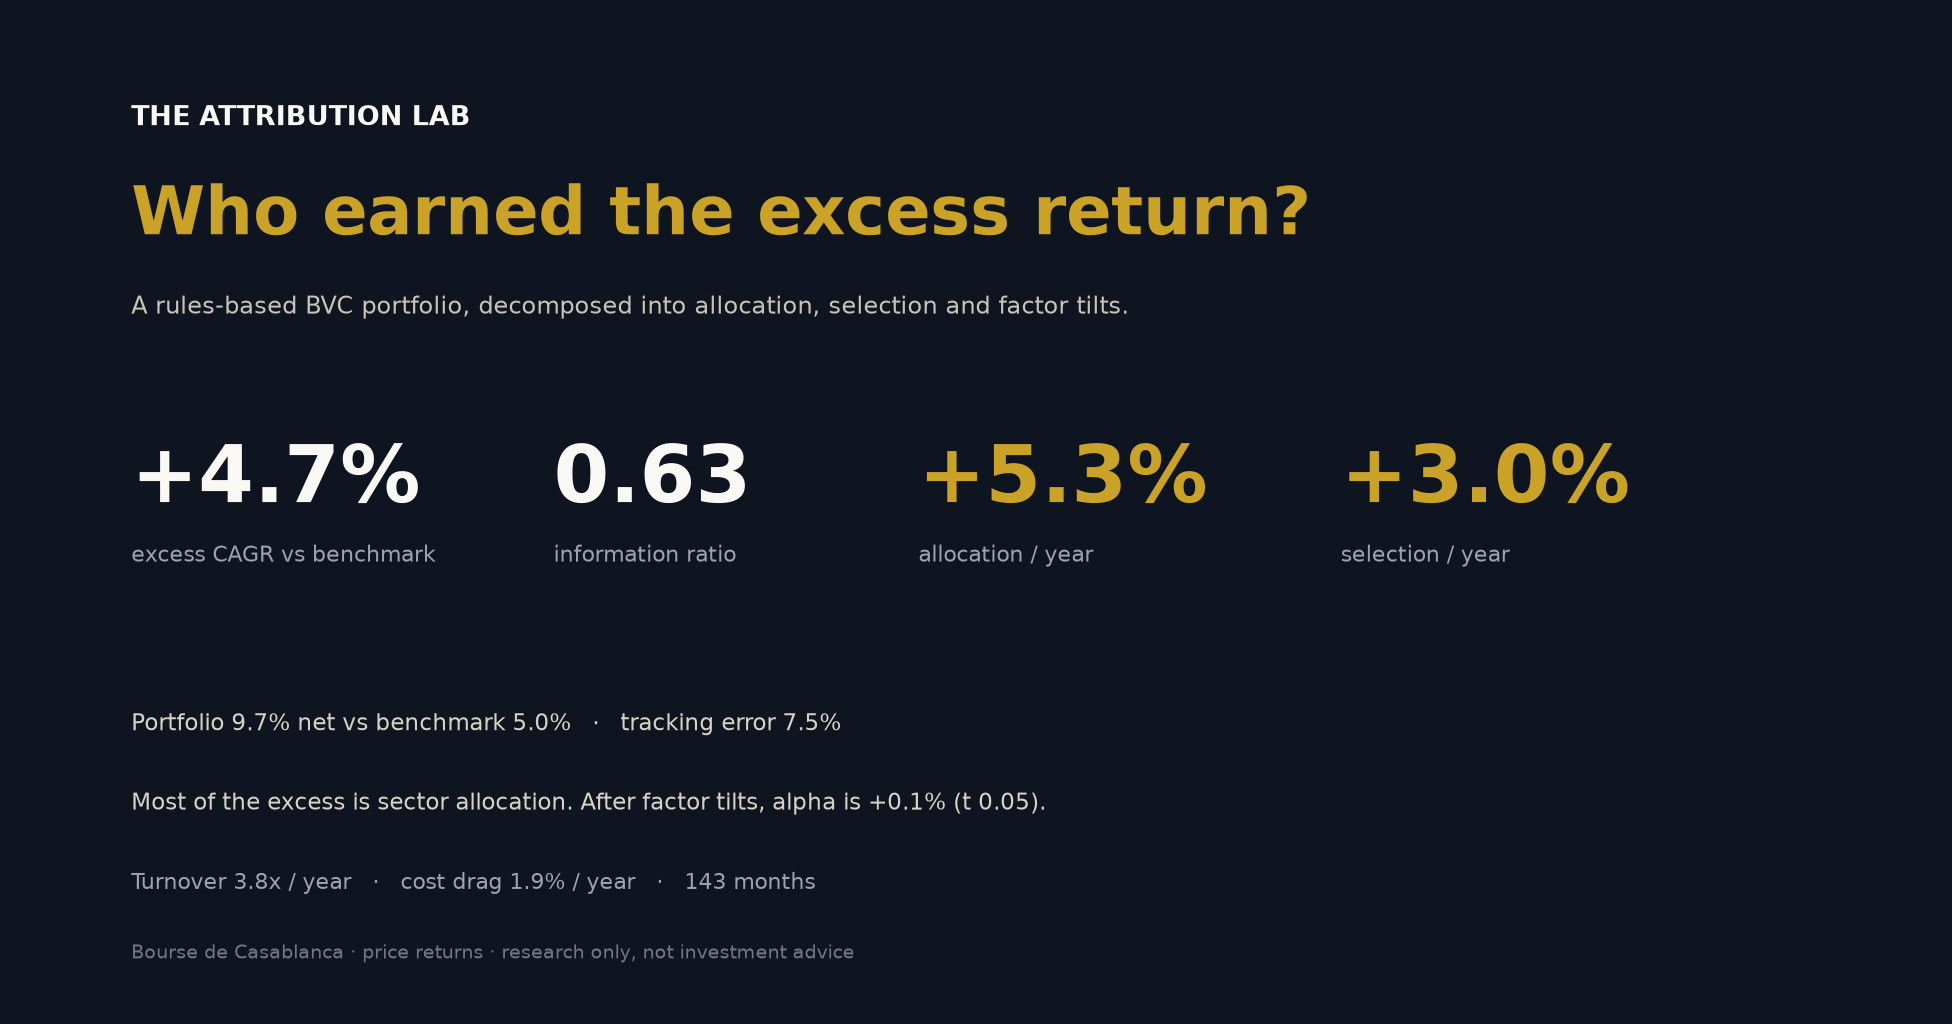
A rules-based 15-name BVC portfolio compounded at 9.7% net against a 5.0% cap-weighted benchmark, a 4.7% annual excess with a 0.63 information ratio. …
+5.3% allocation / yr
Portfolio management · Casablanca
Yirviel Somé — MSc Finance candidate at ENCG Casablanca, FMVA® & BIDA® certified. This is a portfolio-management research desk built in public: mandate, allocation, security selection, risk budgeting and attribution, with corporate finance work alongside it — tested on public filings and Casablanca data.
Watch FIN in motion 01:0101 · portfolio management
I build systematic, evidence-first portfolios: allocation and risk budgeting, factor research, fixed-income and curve hedging, attribution, and the liquidity constraints that decide whether a strategy is actually investable.
Portfolio-management projects →02 · corporate finance
I value companies from their filings: linked three-statement models, DCF and LBO, M&A diligence, accounting quality, and the assumptions that decide the answer.
Corporate-finance projects →evidence · not adjectives
Every card opens the work behind it.
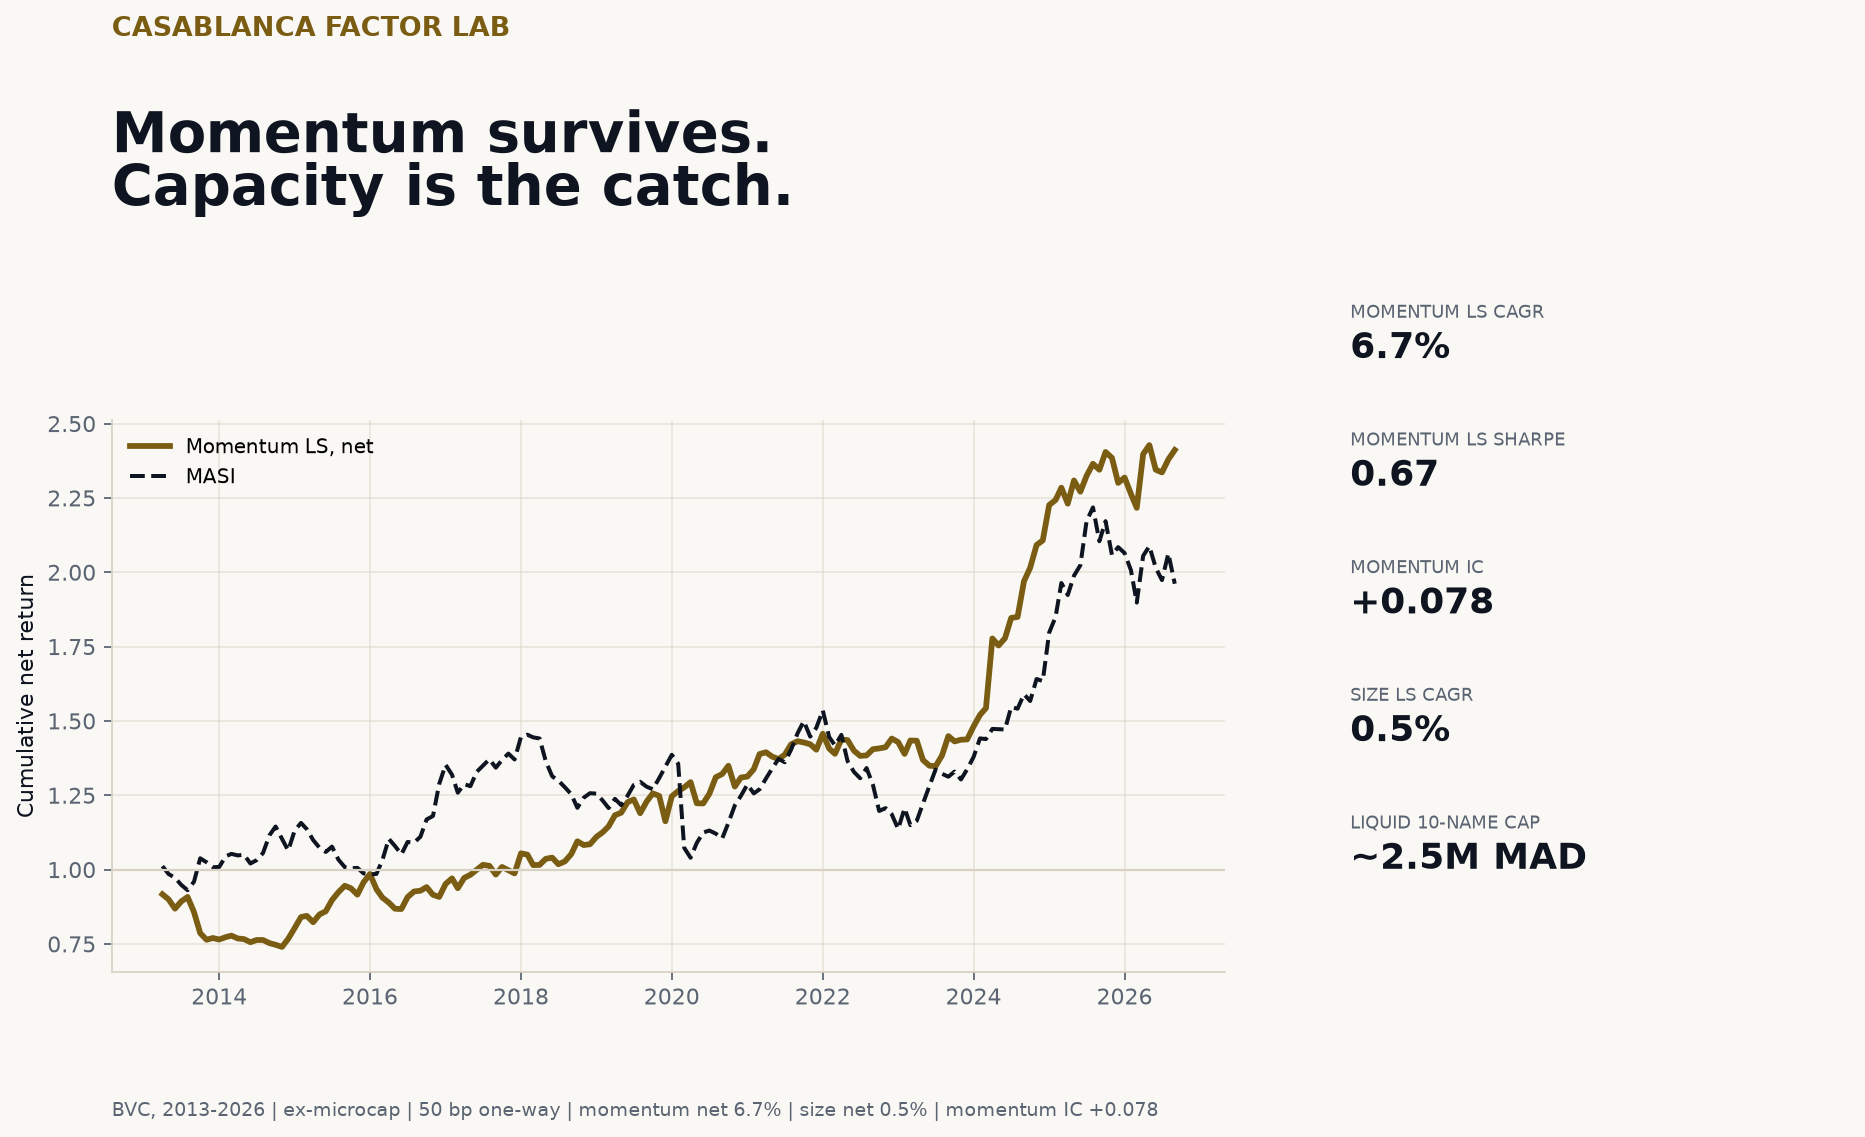
Six factors tested across 13 years of Casablanca data, net of costs, with an ADV-based capacity ceiling. The factor is real; the capacity is not.
Open the factor lab → 02 · risk VaR95% · CVaRA weighted BVC and global-ETF book, measured before the return case: historical VaR and CVaR, drawdown, rolling risk, correlations and stress.
Open the risk dashboard → 03 · attribution +5.3allocation / yrBrinson-Fachler and factor attribution on a rules-based BVC book: 143 months, Carino linking, costs, and an alpha that does not survive the explanation.
Open the attribution lab →01 · the process
A PM is not paid to have views. A PM is paid to turn a mandate into a repeatable process, then defend every step of it. These are the five decisions I train on — in order.
Objective, constraints, horizon, liquidity, and tolerance for loss — written down before a view is formed. The IPS is the contract every later decision is judged against.
The policy portfolio sets the beta. Equity, fixed income, cash, and alternatives are sized by horizon, liquidity, and drawdown tolerance. It is the largest driver of long-run outcomes.
Bottom-up valuation inside the policy bands: DCF, comparables, screens, and factor exposures. A thesis has to survive the filings before it earns a position — and a margin of safety before it earns size.
Covariance, position limits, concentration rules, factor exposures, VaR and CVaR, and stress tests. Risk is sized before the return case: the first question is what breaks the book.
Performance against the policy benchmark, Brinson and factor attribution, rebalancing discipline, and written reporting. The record is the product: returns are explained, not merely reported.
02 · corporate finance
Valuation, leverage, diligence and accounting — built from public filings and public datasets. The secondary pillar: DCF, LBO, M&A and FP&A.
Akdital's three-statement model and DCF, rebuilt from the filings, with the audit that corrected the capex, WACC and terminal-value assumptions.
Open the Akdital DCF → LBO · M&A 17.3% net IRRA full sponsor LBO reconstruction of the CBIZ take-private: leverage, cash sweep, §163(j), management pool, returns and sensitivities.
Open the CBIZ LBO → Diligence · accounting 0raw rows exposedBuy-side diligence without raw data: EBITDA bridge, DSO/DPO/DIO, customer concentration and AR/AP aging on a tokenized ledger.
Open the clean room → FP&A · analytics 8.4% marginA Power BI/FP&A case study from two raw CSVs: a locale trap that would have corrupted 61% of the data, a star schema, and the margin review.
Open the FP&A dashboard →03 · selected projects
Portfolio-management research and corporate-finance models, each built from source data and published with its assumptions, limits and reproduction path.
Portfolio ManagementLab EN
A rules-based 15-name BVC portfolio compounded at 9.7% net against a 5.0% cap-weighted benchmark, a 4.7% annual excess with a 0.63 information ratio. …
Portfolio ManagementLab EN
Momentum is the only factor with a positive, significant premium after excluding microcaps: 6.7% net CAGR, 0.67 Sharpe, 0.078 IC. Size earns 0.5%, the …
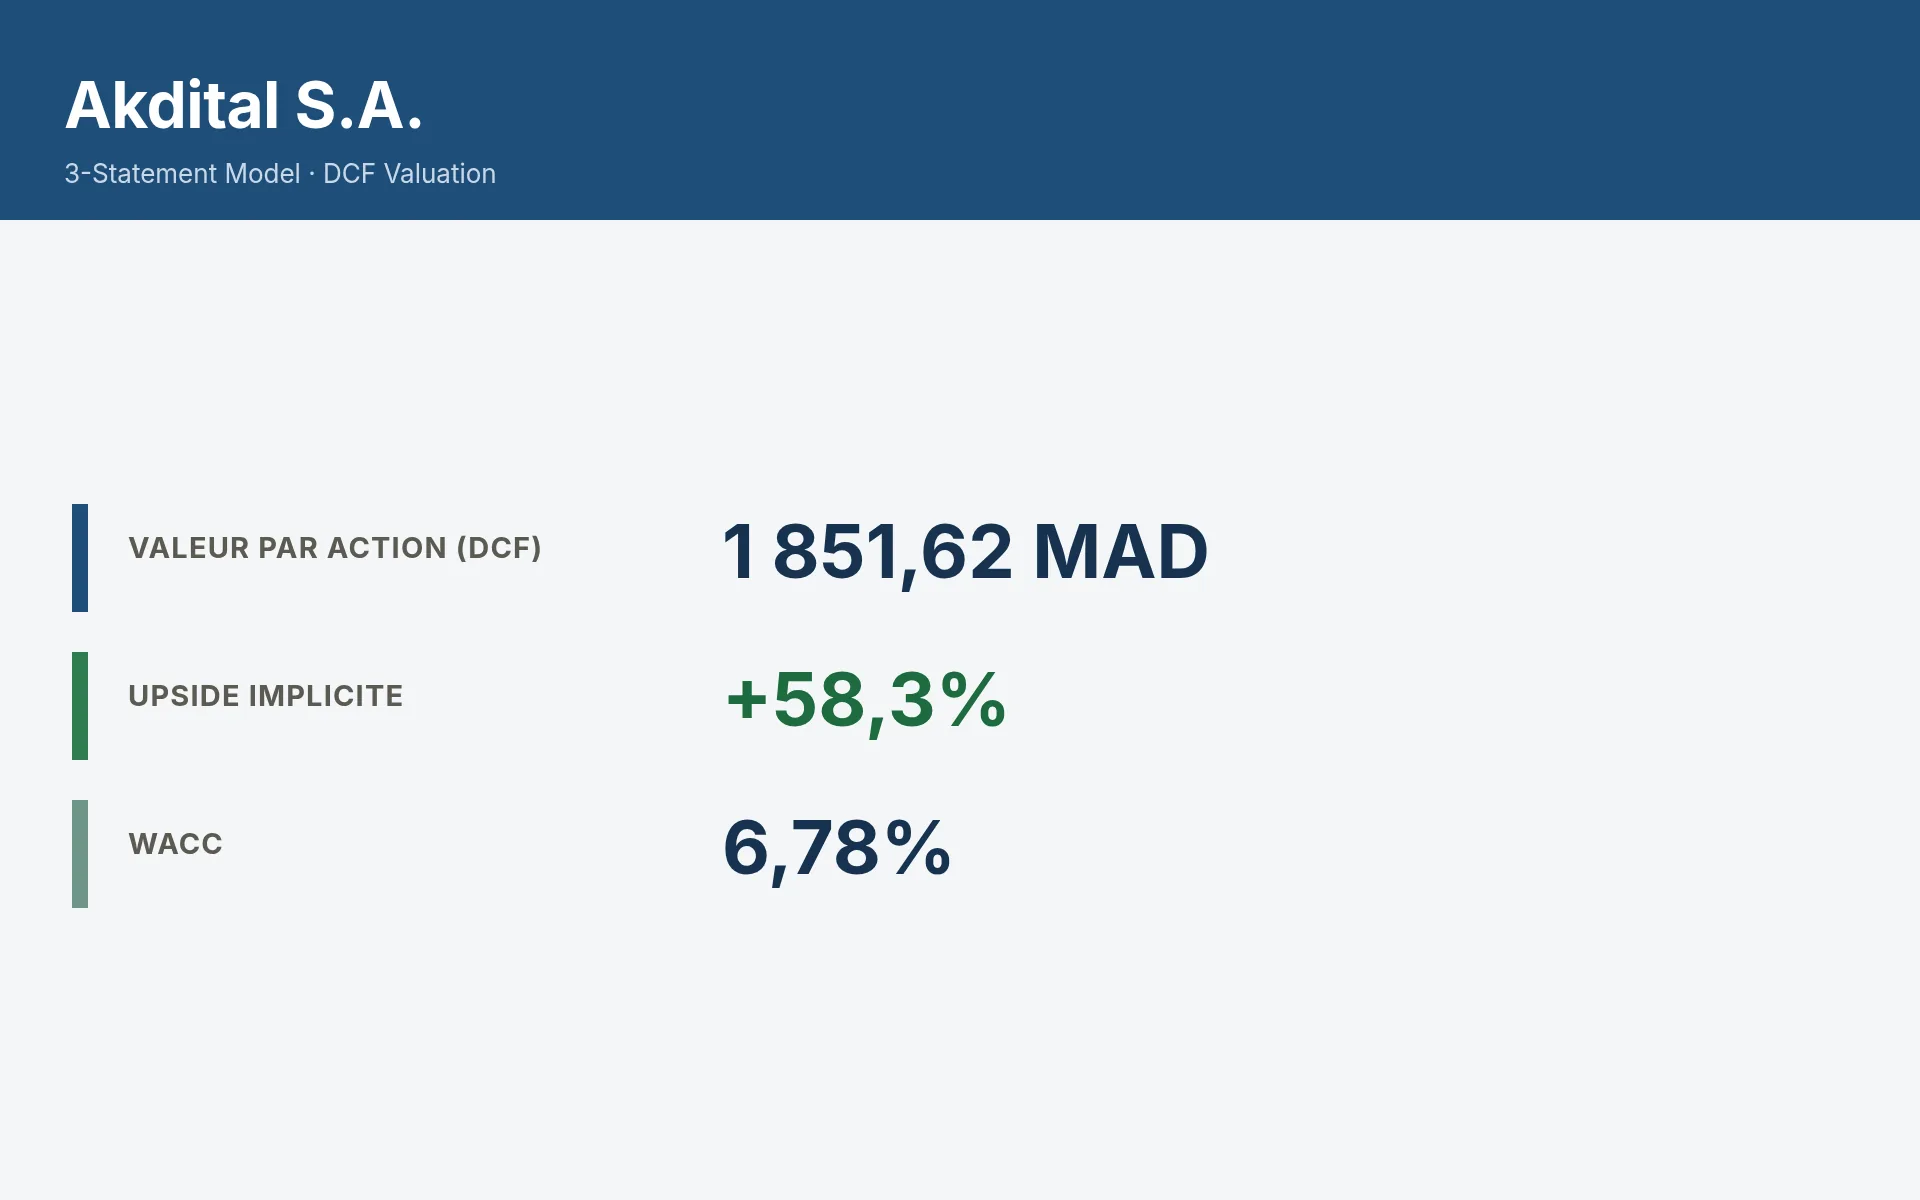
Corporate FinanceCase study FR
Modèle à trois états financiers entièrement lié et valorisation DCF d'Akdital S.A., premier groupe de santé privée coté au Maroc — avec un audit documenté …
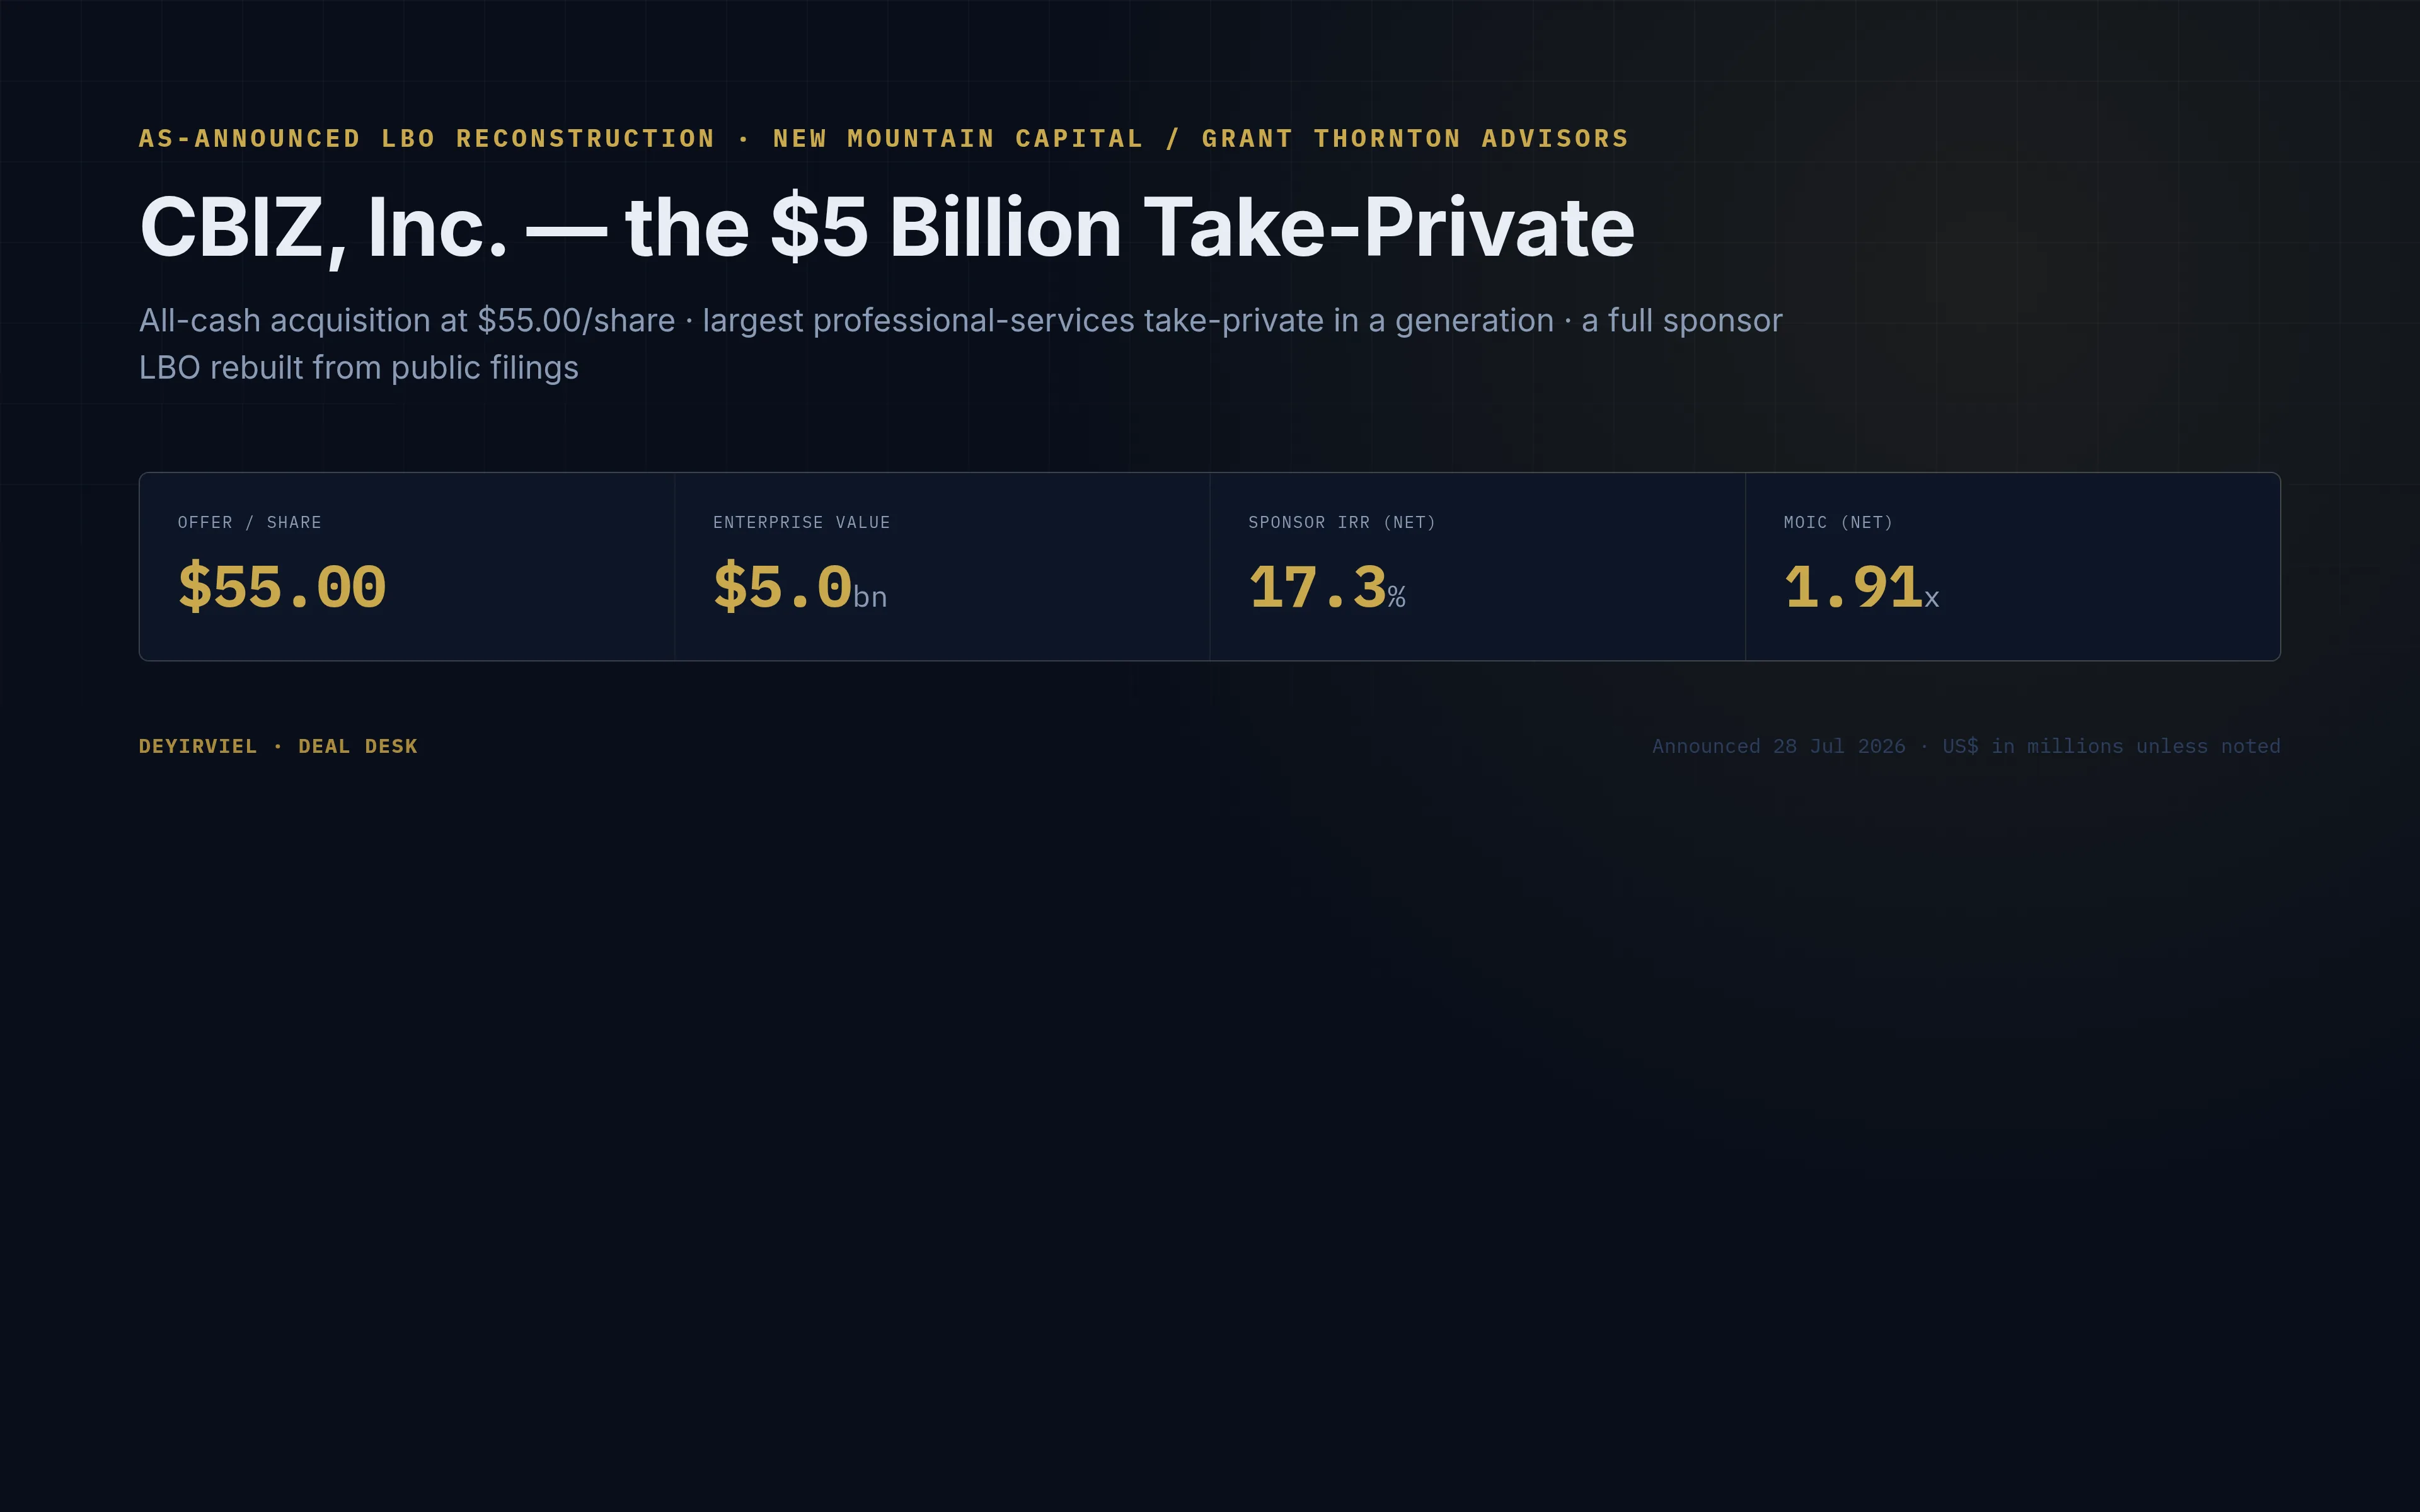
Corporate FinanceModel EN
A seven-exhibit LBO reconstruction of the announced Grant Thornton / New Mountain take-private of CBIZ (NYSE: CBZ) at $55.00/share, $5.0bn enterprise …
04 · tools
The labs are interactive inside the case studies, alongside the standalone DCF, risk dashboard, BAM curve and portfolio Monte Carlo tools. The Projects hub lists every live tool and case study.
Run the linked three-statement DCF: change growth, margins, capex, WACC or terminal value and watch the valuation and balance-sheet checks move.
Open the Akdital DCF → Live · options 2,565SPX quotesPrice an option, inspect the six-expiry volatility surface, and compare delta with delta-gamma hedging.
Open the derivatives lab → Live · fixed income 58.4kMAD / bpFit the BAM curve, reprice the eight-bond book, and move the duration, convexity and key-rate hedge inputs.
Open the BAM curve lab → Live · factors 6.7% net CAGRBlend the BVC factor streams, switch long-only versus long-short, and vary names and transaction costs.
Open the factor lab → Live · attribution 0.63information ratioMove the allocation, selection and cost inputs and watch the Brinson and factor decomposition update.
Open the attribution lab →the seat · investment_team
I am looking for a full-time analyst role on a portfolio management, research, or risk team — allocation, security selection, risk budgeting, and attribution. The work above is the application: open-book, dated, and checkable.
Casablanca or remote · open to full-time analyst roles.
Type to search across portfolio work, corporate finance, notes and pitch exercises.